


Auto insurance fraud is a roughly $40-billion-a-year problem in the United States, and most of the cost lands on honest drivers in the form of inflated premiums. The Coalition Against Insurance Fraud and the Insurance Information Institute estimate that fraud adds several hundred dollars per year to the typical household’s auto insurance bill — money that funds staged accidents, medical mills, phantom repair invoices, and the entire infrastructure of organized rings that have made certain metropolitan areas particularly lucrative to defraud.
This article covers three parallel questions: how honest drivers get targeted by fraud rings they never saw coming, how claims actually get investigated by the insurers’ Special Investigation Units (SIUs) and their rapidly advancing AI detection tools, and how policyholders filing legitimate claims can avoid being incorrectly flagged as suspicious. The three are more connected than they might appear — the same fraud rings that drive up premiums also drive the detection systems that honest policyholders now have to navigate carefully when something goes wrong.
The related questions of how insurance premiums are set and how telematics data gets used in rating are covered in the How Insurers Assess Vehicle Risk and How Telematics Affects Insurance Premiums articles. This piece focuses specifically on the claims side where fraud and legitimate loss meet.
What Insurance Fraud Actually Looks Like
Auto insurance fraud is not one thing. It ranges from an individual padding a legitimate claim with a few hundred dollars of pre-existing dents to organized criminal enterprises that stage dozens of accidents per month using recruited passengers, corrupt body shops, and medical clinics that generate fabricated treatment records. Understanding the landscape is the starting point for understanding why insurers investigate claims the way they do.
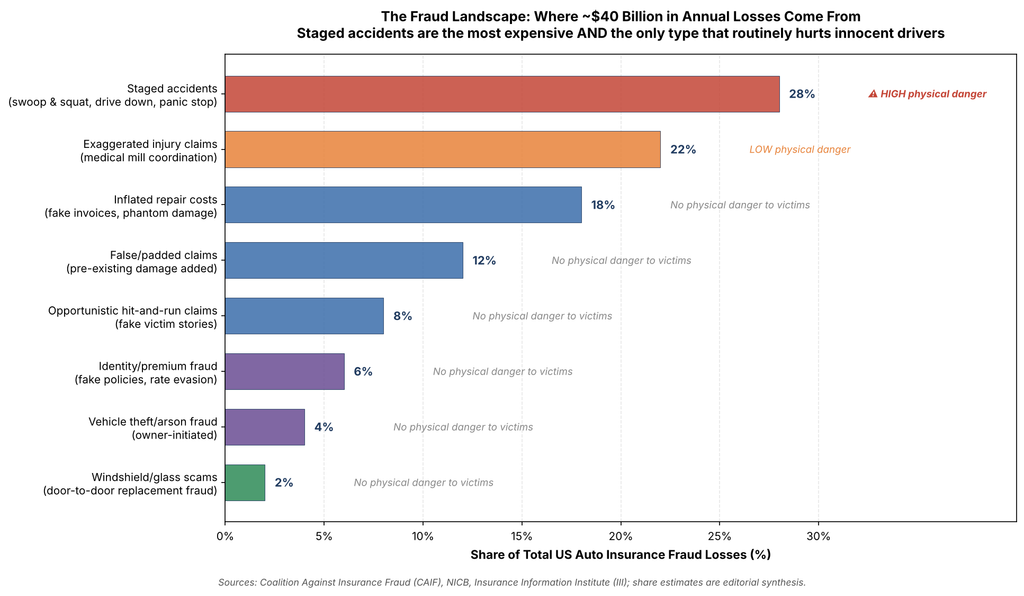
Staged accidents account for the largest single category of fraud losses and are the only type that routinely puts innocent drivers in physical danger. Organized rings deliberately cause collisions with uninvolved motorists, then file coordinated claims through pre-arranged body shops and medical providers. The three most common tactics:
- Swoop and squat: Two fraud vehicles box in a legitimate driver, with the “squat” car suddenly braking in front and the “swoop” car merging to prevent avoidance. The legitimate driver rear-ends the squat car at low speed; multiple passengers in the squat car then claim injuries.
- Drive down: A fraud driver waves another motorist out from a side street or parking lot, pretending to yield right of way, then accelerates into them.
- Panic stop: A fraud driver tailgates another vehicle, then dramatically brakes while the vehicle behind them does the same, timing it so a legitimate driver trailing them has no time to react.
The injury payouts on staged accidents can reach tens of thousands of dollars per passenger when coordinated with cooperating medical providers, which is why the schemes exist despite their high risk profile.
Exaggerated injury claims — the “soft tissue” fraud problem — involves real accidents where claimants inflate injury severity, extend treatment timelines, or claim injuries that did not occur. Medical mills (clinics that specialize in generating claim-supporting documentation for a fee or kickback) coordinate with personal injury attorneys and claimants in a well-established pattern.
Inflated repair costs involves body shops and mechanics overcharging for legitimate repairs, charging for work not performed, or adding phantom damage to claims. The shop and claimant typically split the overage.
False and padded claims means adding pre-existing damage to a new claim, claiming total loss of items that never existed in the vehicle, or submitting duplicate claims through multiple insurers.
Opportunistic hit-and-run claims involves claimants fabricating hit-and-run scenarios to claim damage from events that never occurred, often tied to pre-existing vehicle damage the owner needs repaired.
Identity and premium fraud covers people opening policies under false identities, lying about where a vehicle is garaged to get lower rates, or claiming a vehicle is not used for business or rideshare when it actually is. This is a different kind of fraud — stealing from the insurer rather than coordinating a false claim — but still accounts for several billion dollars annually.
Vehicle theft/arson fraud is owner-initiated insurance fraud where the owner arranges for their own vehicle to be stolen or destroyed, usually because they owe more than it’s worth or the vehicle has mechanical problems that would cost more to fix than selling.
Windshield and glass scams are the smallest category but the most visible to average consumers — door-to-door salespeople offering “free” windshield replacement to anyone with the slightest chip, then filing claims against the owner’s insurance for much more than the work was worth.
Where Fraud Is Concentrated
Insurance fraud is heavily geographic. Certain metropolitan areas have organized ring infrastructure that generates most of the staged-accident volume, and premium rates in those regions reflect it. A driver with an identical profile pays substantially more in Miami, NYC, or Los Angeles than in a comparable Midwest metro largely because the claim frequency and severity in high-fraud regions are higher.
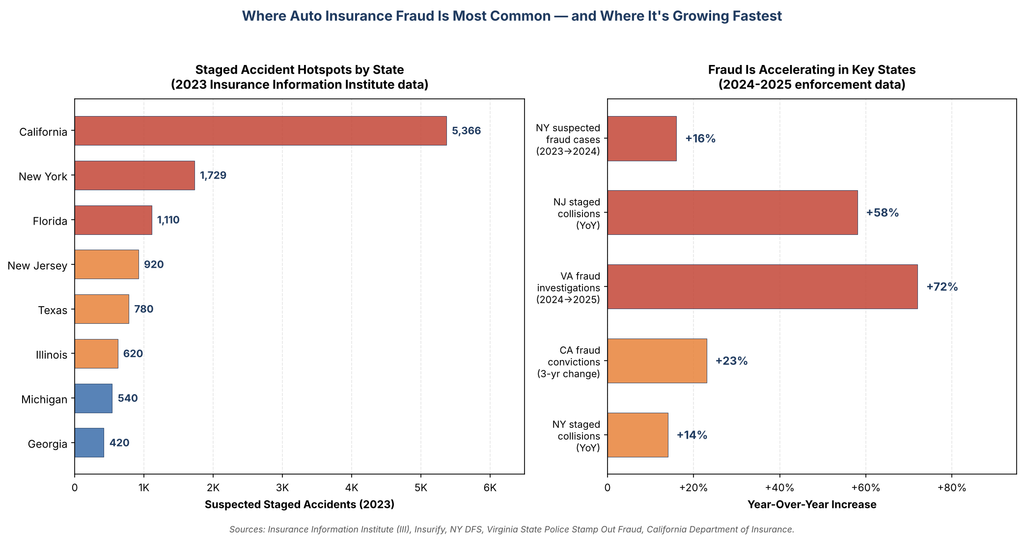
California recorded 5,366 suspected staged accidents in 2023 — more than any other state by a wide margin — per Insurance Information Institute data. California’s Department of Insurance has responded with aggressive prosecution, with criminal insurance fraud convictions up 23% over the three years ending in 2025. The sheer size of the state’s driving population means California will likely remain the largest absolute fraud market even as per-capita rates vary.
New York reported 1,729 suspected staged accidents in 2023 and 44,361 total suspected motor-vehicle fraud cases in 2024 — a 16% year-over-year increase. In 2025, Governor Hochul announced a statewide crackdown on staged collisions, including multiple ring arrests. New York’s no-fault insurance structure — which guarantees medical payments regardless of fault — has historically made the state attractive to medical mill schemes.
Florida reported 1,110 suspected staged accidents in 2023. Florida’s personal injury protection (PIP) system creates similar dynamics to New York’s no-fault structure, and the Miami-Dade, Broward, and Tampa metropolitan areas have persistent fraud ring activity.
New Jersey recorded 920 suspected cases in 2023 but saw staged collisions jump 58% year-over-year — the highest rate of increase in the country.
Virginia saw a 72% increase in fraud investigations from 2024 to 2025 through its Stamp Out Fraud program — a reflection of aggressive new enforcement rather than a sudden surge in criminal activity, but indicative of how much fraud goes undetected without dedicated investigation resources.
Michigan, despite having only 540 suspected cases in 2023, has historically had one of the highest auto insurance premium rates in the country because its no-fault system creates similar fraud incentives to New York’s. Michigan’s 2019 no-fault reforms have modestly reduced fraud since, but ring activity remains significant.
The common thread across hotspots is population density plus favorable claim structures — specifically no-fault and PIP systems that pay claims without requiring fault determination, creating opportunities for staged events that generate guaranteed payouts. States without those structures (most of the Midwest and South) have substantially lower ring activity despite comparable traffic volumes.
How Fraud Rings Target Honest Drivers
The disturbing part of the staged-accident problem is that it targets random, uninvolved drivers. Most people who have been victims of swoop-and-squat or drive-down schemes had no prior connection to the fraudsters — they were simply convenient targets at the wrong moment. A few practical defenses:
Maintain safe following distances at all times. The three-second rule exists for physics reasons, but it’s also the single most effective defense against staged-accident schemes. Nearly every staged accident scheme depends on the target vehicle being unable to stop in time.
Be especially cautious of waved-on invitations. If another driver is signaling you to merge, pull out, or proceed — especially in heavy traffic, at parking lot exits, or at busy intersections — assume they may be setting you up. If an accident occurs, their “I never waved you on” testimony will dominate the police report.
Dash cameras are the single most effective fraud deterrent available to individual drivers. A front-facing dash cam (and ideally rear-facing too) captures the actual event in real time, making the swoop-and-squat and drive-down tactics unworkable. Dash cams cost $80-300 and have become near-universal among commercial fleet operators specifically because of fraud concerns. Many insurers now offer modest discounts for verified dash cam installation.
Be skeptical of parties who arrive at the scene suddenly. Ring operations often have a nearby tow truck driver, “witness,” or lawyer business card distributor who arrives within minutes. Legitimate accidents don’t attract specific tow operators pushing specific body shops pushing specific attorneys.
Call 911 and request a police report for any accident, even minor ones. Rings prefer to settle at the scene with a quick exchange of information and no police involvement. A police report creates an official record of injuries claimed (or not) at the scene, which makes later injury claims harder to inflate.
Document the scene before any vehicle is moved, if conditions safely permit. Photos of final resting positions, debris patterns, skid marks, and occupant locations become very hard to fabricate after the fact.
Request names and ID of all occupants, not just the driver. Most staged-accident injury claims come from passengers — multiple of them, often three or four in a single compact car — who were allegedly all seriously injured in a minor-impact rear-ending. Having their names documented at the scene makes later discovery of ring connections possible.
Never admit fault at the scene. Even if you think you’re at fault, let the investigation determine it. In staged accidents, you are almost by definition not the party at fault even when physics suggests you rear-ended them.
Report suspicious accident characteristics to your insurer promptly. If something about the circumstances felt off — multiple passengers claiming injuries from a minor impact, the other driver being too calm about being hit, the arrival of a specific lawyer or tow truck within minutes — tell your insurer. SIU investigators are trained to recognize ring patterns across multiple claims and your observation may trigger an investigation that stops the ring.
The Assessing Seller Credibility in Private Car Sales article covers related fraud detection in a different context; some of the same instincts (if it feels off, it usually is) apply.
How Insurers Actually Detect Fraud in 2026
The insurance industry’s fraud detection has advanced substantially over the last decade, and the gap between what fraud rings assume insurers can do and what they actually can do has narrowed significantly.
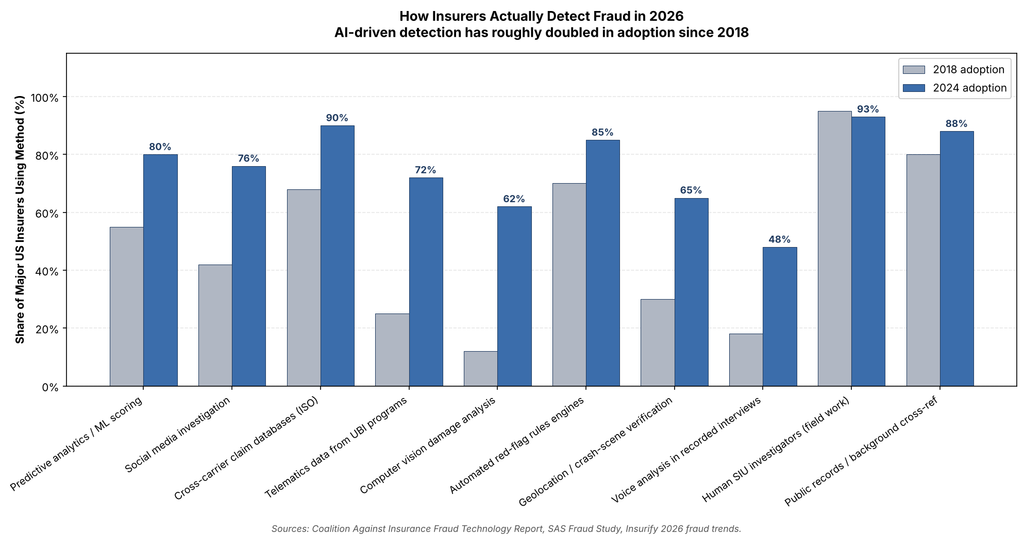
Predictive analytics and machine learning scoring are now used by 80% of major US insurers, up from 55% in 2018. Every incoming claim gets scored against models trained on millions of past claims; outliers on dozens of dimensions get flagged for review. The models detect patterns a human adjuster would miss — unusual pairings of policy age and claim size, specific combinations of providers appearing across multiple claims, geographic clustering of similar claim narratives.
Cross-carrier claim databases (primarily ISO ClaimSearch) are used by 90% of insurers and allow matching individual claimants against their claim history at any other participating carrier. A claimant with a history of suspicious claims at Allstate who files with GEICO shows up in the database immediately. Medical providers, attorneys, and body shops get similarly matched — a pattern of showing up in many different claimants’ files is one of the strongest fraud indicators.
Automated red-flag rules engines flag claims that match specific patterns — accident reported to insurer before to police, injury claims by passengers but not drivers, specific attorney/doctor pairings known to be associated with fraud rings, treatment that extends past specific thresholds without supporting diagnostic evidence. These engines don’t reject claims automatically but route flagged claims to human investigators.
Social media investigation has grown from 42% to 76% adoption since 2018. SIU investigators routinely check claimants’ public social media for photos or posts that contradict injury claims — the classic “claimant said they couldn’t lift their arm, posted videos of themselves at CrossFit the following week” scenario is more common than it should be, and investigators specifically look for it.
Telematics data from UBI programs is now used by 72% of insurers in fraud investigation, up from 25% in 2018. If a driver enrolled in Progressive Snapshot or State Farm Drive Safe & Save files an accident claim, the underlying telematics data can be pulled to verify time of accident, approximate speed, impact force, and location — any mismatch with the claim narrative becomes investigable. This is one of the significant trade-offs of UBI enrollment covered in the How Telematics Affects Insurance Premiums article.
Computer vision damage analysis has moved from pilot to production, with 62% of major insurers now using some form of automated damage assessment on claim photos. The AI compares damage patterns to known crash physics, flagging cases where damage doesn’t match the described accident — a rear-end impact with damage patterns suggesting the vehicle wasn’t moving forward at the time, for instance. Companies like Click-Ins, Tractable, and CCC Intelligent Solutions provide the underlying technology.
Geolocation and crash-scene verification cross-references claim locations with traffic data, weather data, and road conditions at the stated time. A claim describing heavy rain on a day with no precipitation in the area becomes immediately suspicious.
Voice analysis of recorded claimant interviews is a newer capability, growing from 18% to 48% adoption. Linguistic patterns associated with deception — unusual pronoun avoidance, inconsistent tense usage, excessive justification — get flagged by software even when human interviewers miss them.
Human SIU investigators remain central despite all the automation. 93% of insurers maintain dedicated Special Investigation Units; the automation generates leads for SIU to investigate rather than replacing human judgment. SIU investigators conduct recorded statements, surveillance, provider interviews, and the detailed documentation that supports fraud prosecution.
Public records and background cross-reference — court records, bankruptcy filings, previous fraud charges, business registrations — are standard checks for high-value claims and anyone with multiple claim history.
The combined effect is that fraud rings operating in 2026 face substantially more detection capability than in 2018, but also more sophisticated fraud ring operation that has adapted to the detection. The arms race continues.
Red Flags That Make Insurers Suspicious
For a legitimate policyholder filing a legitimate claim, the question is what characteristics of a claim trigger the investigation flags in the first place. Knowing this is useful both for avoiding being incorrectly flagged and for understanding when extra documentation is worth providing.
The red flags SIU investigators look for include:
- Claims filed shortly after policy inception. A claim within the first 30 days after a new policy starts gets more scrutiny because new-policy fraud is a specific category. Legitimate claims on newly-started policies happen (people switch insurers all the time), but expect extra documentation requests.
- Significant gaps in coverage history. A driver who had no coverage for the previous year, bought a new policy, and files a claim within weeks gets extra attention.
- Multiple claims in a short period. Several claims within 12-24 months — even if each is small and legitimate — raises the composite risk profile.
- Injuries not reported at the scene. Soft-tissue injury claims that first appear days or weeks after the accident get much more scrutiny than injuries documented in the initial police report.
- Treatment with specific providers known for fraud associations. This is why medical providers’ claim histories matter; if the provider has shown up across many suspicious claims, your legitimate claim through them inherits scrutiny.
- Representation by specific attorneys who appear across many ring-associated claims. Same dynamic as the medical providers.
- Damage patterns that don’t match the described accident. A rear-end collision where your front has significant damage but the other party’s rear has none. A side-impact with damage on the wrong side of the vehicle.
- Unusual timing or circumstances. 3 AM single-vehicle accidents on deserted roads. Accidents in parking lots with no witnesses. Accidents in which both drivers conveniently waited until they got home to call insurance.
- Changes to the claim narrative over time. The first version mentioned only one injury; the second version mentioned three. The first version said 25 mph; the second version said 45 mph. Any material inconsistency between statements raises the suspicion level significantly.
- Reluctance to provide documentation or allow inspection. Refusing to produce the vehicle for inspection, declining to provide medical records, or stonewalling specific questions is often the single clearest fraud signal.
What Legitimate Claimants Should Actually Do
The best protection against being incorrectly flagged is the same set of practices that make any claim move faster and get paid correctly. For a legitimate accident:
Call 911 and get a police report at the scene. The police report is the foundational document for the claim; without it, every subsequent step is harder and slower.
Photograph everything before vehicles are moved, if conditions safely permit. Photos of all damage, final vehicle positions, debris patterns, road conditions, license plates, and the surrounding scene. Phone photos with metadata (location, timestamp) carry more evidentiary weight than most people realize.
Get witness contact information immediately. If strangers stopped to help, get their names and phone numbers before they leave. They become hard to locate later and independent witness testimony is one of the most powerful tools in a legitimate claim.
Document any injuries at the scene with specific terms. “I feel fine” said at the scene and captured on the officer’s body camera becomes a serious problem if you later develop neck or back pain. Soft tissue injuries often don’t present symptoms immediately; the appropriate statement is “I’m not sure, I don’t think I’m injured but I want to get checked out.”
Call your insurer the same day, even before medical visits. The timing of the first call matters.
Keep all repair estimates, medical bills, and related paperwork in a single file. Insurers will request specific documents at various points; having everything organized shortens the process.
Be honest about everything, including things that make you look bad. The quickest way to turn a legitimate claim into a fraud investigation is to lie about something small — a cell phone that was in your hand, a cup of coffee that was in your other hand, the fact that you’d been driving longer than you should have been. Insurers detect these inconsistencies routinely; being caught in a small lie makes everything else you say suspicious.
Respond promptly to requests from the insurer. Slow responses or unresponsive communication are themselves red flags. Return calls within 24 hours when possible.
Don’t exaggerate. If your actual medical bills are $3,200, claim $3,200, not $5,000. Padding a claim with legitimate underlying facts turns a legitimate claim into fraud.
Don’t settle at the scene with the other party, even if they offer cash. Scene settlements with no claim documentation make your later claim suspicious if symptoms develop.
Consider getting an attorney if the accident was serious. Not every accident requires legal representation, but for anything involving significant injury or disputed fault, a legitimate personal injury attorney (not one who approached you at the scene) provides important procedural guidance.
What Happens When a Claim Gets Flagged
If your claim does get flagged for SIU investigation, the process looks different from normal claim handling. A flagged claim typically involves a recorded statement (sometimes called an Examination Under Oath, or EUO), requests for extensive documentation, possible surveillance, and interviews with medical providers, witnesses, and anyone else involved.
The process is not inherently adversarial — most flagged claims are ultimately resolved as legitimate and paid out. But it takes substantially longer (often 60-180 days versus the 2-4 week timeline of an unflagged claim), requires more active engagement from the claimant, and ultimately produces a determination documented in both your insurer’s records and the industry-wide ISO ClaimSearch database.
Specific tips if your claim is under SIU investigation:
- Take the recorded statement seriously. Prepare for it. Review the accident timeline. Have supporting documents available during the call. Answer questions honestly and don’t speculate.
- Comply fully with documentation requests. Refusing to provide medical records or vehicle inspection access is interpreted as consciousness of fraud, regardless of your actual intent.
- Keep detailed notes of every interaction with the insurer — dates, names, what was discussed, what was requested.
- Consider consulting an attorney if the investigation extends beyond 60 days or if the insurer begins denying portions of the claim. Policyholder-side attorneys who specialize in bad-faith insurance litigation can be valuable.
- Don’t take it personally. SIU investigators investigate because the algorithm flagged your claim, not because they think you’re a criminal. Most investigations end with full payment and a note in the file.
The Takeaway
Auto insurance fraud is bigger, more organized, and more geographically concentrated than most honest drivers realize. It costs roughly $40 billion annually, with staged accidents by organized rings accounting for the largest single share and the only category that routinely endangers innocent drivers. California, New York, Florida, New Jersey, and a handful of other hotspot states contain most of the ring activity, though enforcement has been accelerating in several of them.
For individual drivers, the practical defenses against being targeted are straightforward: dash cameras, safe following distances, caution around waved-on invitations, 911 calls at the scene of any accident, and skepticism of parties who arrive suddenly to help. For filing legitimate claims, the key practices are honest documentation, prompt communication, and careful avoidance of exaggeration — because the AI-driven and human-driven fraud detection systems that chase rings also scrutinize ordinary claims, and the trail of small inconsistencies that triggers investigation is often indistinguishable between fraudulent and sloppy filing.
The detection capability on the insurer side has roughly doubled since 2018 across most metrics — predictive analytics, social media, telematics, computer vision, cross-carrier databases. For claimants with nothing to hide, this mostly means faster payment on clean claims. For claimants whose circumstances happen to resemble fraud patterns, it means longer investigations and more documentation requests. For the actual fraud rings, it means a rising cost of operation that is slowly compressing the margins they’ve relied on for years.
The related questions of how premiums get set, how telematics data gets used, and how insurers interact with claims more broadly are covered in the How Insurers Assess Vehicle Risk, How Telematics Affects Insurance Premiums, and Why EVs Have Different Insurance Costs articles.
External Sources
Cameramatics — Top 5 Crash-for-Cash Insurance Scams
Coalition Against Insurance Fraud — Annual Fraud Statistics
NICB — Auto Insurance Fraud on the Rise
Insurify — Tighter Enforcement Driving Rising Auto Insurance Fraud Numbers
Insurance Journal — Staged Auto Accidents: A Costly Threat for Fleets
Ethos Risk — What’s the Real Cost of a Staged Auto Accident?
Fox Business — Auto Insurance Fraud on the Rise in US
Insurance Information Institute — Background on Auto Fraud
BeInsure — New York Arrests 16 in Auto Insurance Fraud Crackdown
Insurance Journal — 15 Californians Charged in Complex Auto Fraud Ring
MoneyGeek — Protecting Against Auto Insurance Fraud
PYMNTS — Click-Ins Taps AI to Enhance Vehicle Damage Detection
Ethos Risk — How AI Is Transforming Auto Accident Investigations



Leave a Reply
You must be logged in to post a comment.